One market order sold 125,283 RUJI into the FIN RUJI/USDC book in a single block, filled a quarter under the base pool, and left FIN 40 % below the pool until arbitrageurs closed the gap a minute later.
RUJI sold
125,283
USDC received
15,610
Average price
0.1248
Under the pool
−25.5 %
Fills
535
Cost vs pool
≈ $5,380
To arbitrageurs
≈ $2,100
Gap closed in
≈ 1 min
On 5 November 2026 at 07:41:34 UTC
one transaction
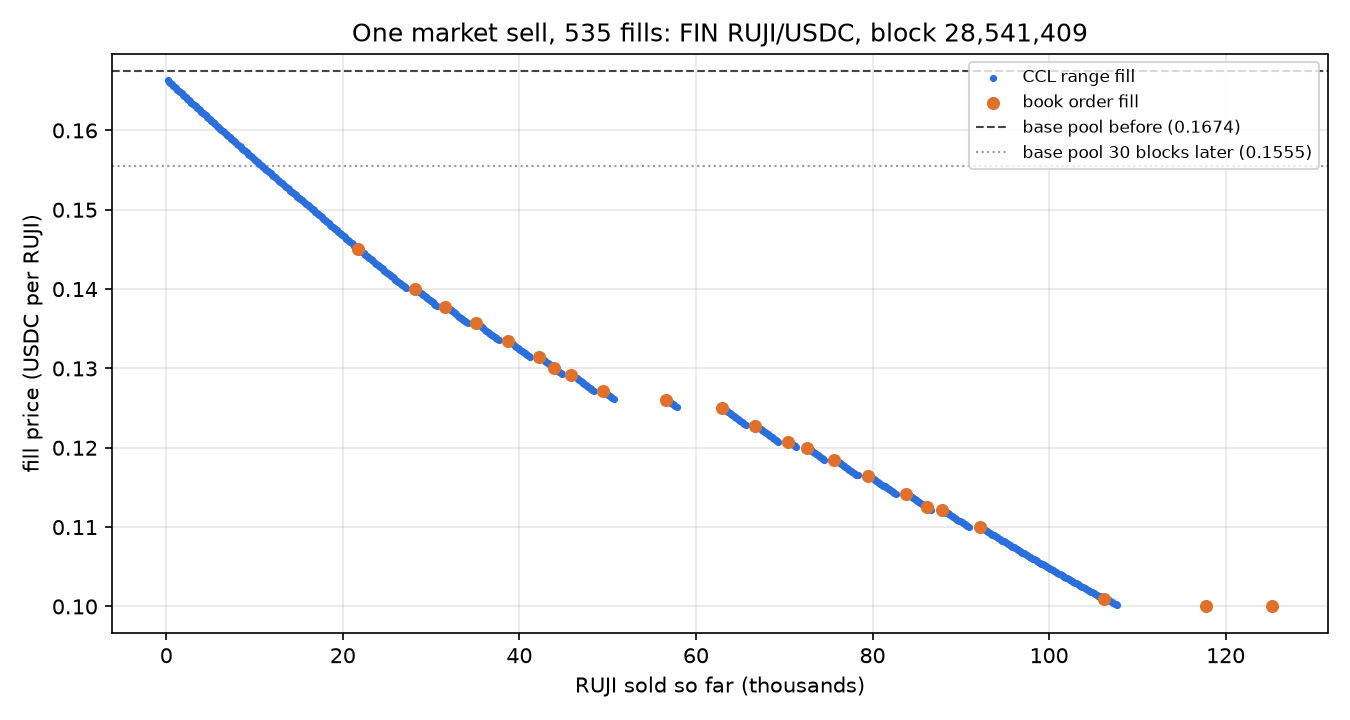
sold 125,283 RUJI into the FIN RUJI/USDC order book in a single market order. It walked the book
from 0.1663 down to 0.1000 USDC per RUJI, paid about a quarter under the base-layer pool's price,
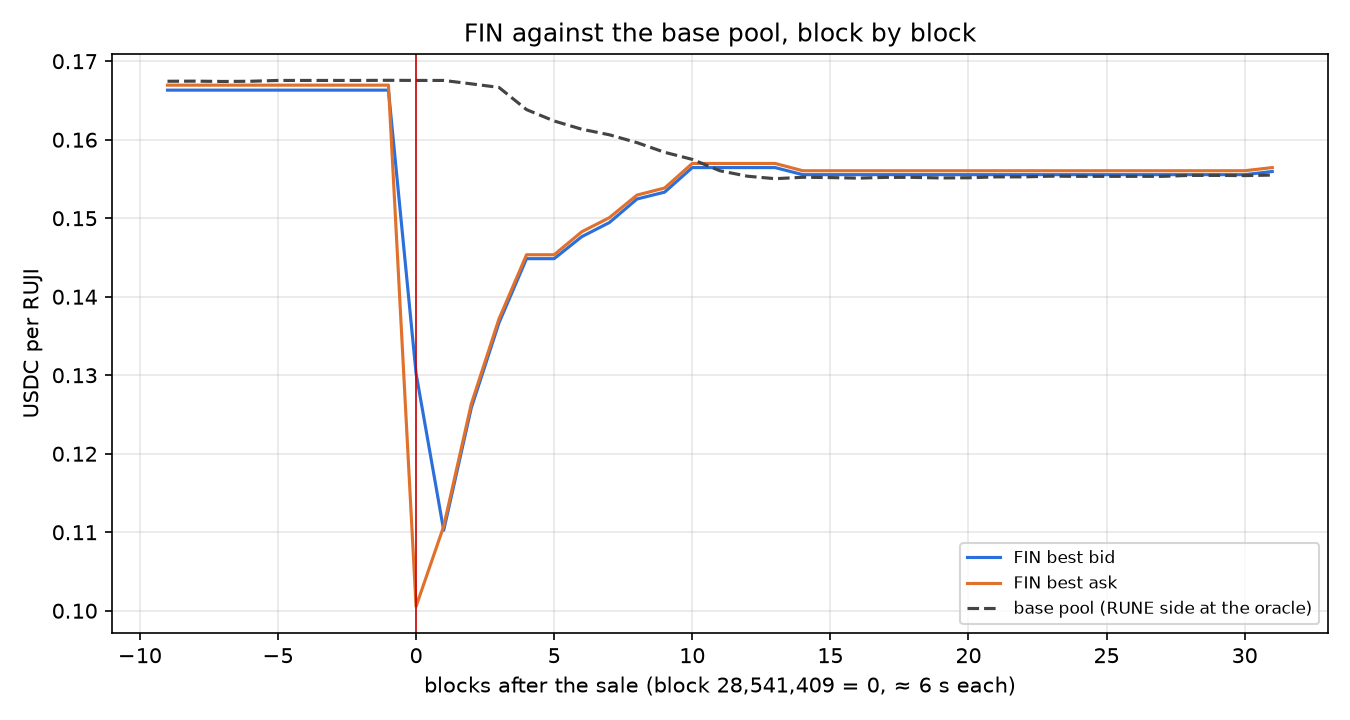
and left FIN up to 40 % under the pool for about ten blocks until arbitrageurs closed the gap.
Every number below comes from THORChain's own events and state at the block it names. Amounts read
straight from events are marked
exact.
Figures that value a mix of assets at a price are marked
estimate.
The sale
The seller was a holder leaving the Rujira ecosystem: minutes earlier it had unstaked its
sRUJI into 125,032 RUJI. Then one
MsgExecuteContract
on the FIN RUJI/USDC contract sold
125,283.02 RUJI
at market. No base-layer swap took part, and the RUJI base pool was untouched by the sale itself.
512 fills · CCL ranges · exact
80,296.72 RUJI
for 10,460.12 USDC
23 fills · book orders · exact
44,986.30 RUJI
for 5,173.67 USDC
In all 15,633.78 USDC, of which the seller received
15,610.33 USDC.
The market's 0.15 % taker fee was 23.45 USDC. The average price was
0.12479 USDC per RUJI:
the first fill went at 0.16632, the last at 0.10000.
Each of the 535 fills, in order. Blue: CCL ranges. Orange: book orders.
The CCL ranges priced the first 50,000 RUJI along a smooth curve. Each range quotes along its own
liquidity curve, so a large sell moves along all of them at once. The book orders were single levels
on the way down, most of them 135 USDC bids about 1.6 % apart, which looks like one grid of orders.
The last 17,000 RUJI went to two large bids at 0.1001 and 0.1000.
What it cost the seller
The base pool priced RUJI at
0.16753 USDC
just before the sale. At that price the 125,283 RUJI were worth ≈ $20,989 and sold for $15,610:
≈ $5,380 (25.5 %) under the pool.
Thirty blocks later arbitrage had pushed the pool itself down to 0.15548, and against that price the
shortfall is ≈ $3,870.
Estimate.
The book, block by block
Just before the sale, the book held
≈ 497 USDC of bids
within 2 % of the mid. The order was about forty times that. Prices in USDC per RUJI.
Block
Seconds
FIN bid
FIN ask
Base pool
FIN ask vs pool
28,541,408
−6
0.1663
0.1669
0.1675
−36 bps
28,541,409 · sale
0
0.1302
0.1006
0.1676
−3,998 bps
28,541,410
6
0.1102
0.1107
0.1676
−3,390 bps
28,541,411
12
0.1258
0.1263
0.1671
−2,439 bps
28,541,412
18
0.1366
0.1371
0.1667
−1,770 bps
28,541,413
24
0.1448
0.1453
0.1638
−1,128 bps
28,541,415
36
0.1476
0.1483
0.1613
−809 bps
28,541,417
50
0.1524
0.1529
0.1596
−418 bps
28,541,419
62
0.1564
0.1570
0.1575
−32 bps
28,541,422
80
0.1564
0.1570
0.1550
+125 bps
28,541,440
191
0.1559
0.1564
0.1555
+59 bps
FIN's best bid and ask against the base pool, six seconds per block.
Right after the sale the book was crossed:
a bid at 0.1302 stood above an ask at 0.1006. The CCL ranges re-priced around their new balances,
and the ladder of bids and asks no longer lined up.
From the next block, arbitrageurs bought RUJI on FIN and sold it into the base pool. FIN rose from
0.110 to 0.156 and the pool fell from 0.1675 to 0.1555.
The two met about ten blocks later, around 07:42:36 UTC.
Who bought the RUJI at the bottom
Ten CCL ranges took 80,110 RUJI for 10,460 USDC (exact: each range's balance before and after the
block). Two of them took 94 %, and both span very wide bands.
Range
Band (USDC)
RUJI bought
USDC paid
Avg price
#66
0.01 – 15
62,350
8,063
0.1293
#197
0.0135 – 0.3016
12,653
1,635
0.1292
#198
0.13 – 0.30
2,531
373
0.1473
#153
0.15 – 0.27
1,054
167
0.1584
six others
1,523
222
0.146
The book orders took 44,986 RUJI for 5,174 USDC, at 0.1150 on average. At the pool price thirty blocks
later, what these buyers took was worth
≈ $3,815 more than they paid
— essentially the seller's shortfall at that price. They kept the RUJI, so this is not a realised
profit.
Estimate.
Who arbitraged it back
Every address that traded the FIN market or the RUJI base pool in the 191 seconds after the sale,
valued by its net change in every asset at the prices thirty blocks later.
Estimate.
Started
How
≈ USD
Arbitrageur 1
next block
ten FIN-only cycles through the Liquidy router, out of BTC and USDT and back
1,064
Arbitrageur 2
+2 blocks
bought 10,491 RUJI on FIN, sold it into the base pool
440
Arbitrageur 3
next block
FIN cycles out of its own inventory
415
Arbitrageur 4
+2 blocks
FIN buys, then 15 sells of 1,300–3,300 RUJI into the base pool
134
Arbitrageurs 5–11
+2 blocks
base-pool swaps, FIN plus base pool
70
About $2,100 went to arbitrageurs, two-thirds of it to the two that traded in the very next block.
The gap they closed was paid for by the pool, whose RUJI price they pushed down 7 %, and by the ranges,
which sold part of their cheap RUJI back up the curve.
Takeaways
A market order on a thin book is expensive
Within 2 % of the price there were about $500 of bids for a $21,000 sale. The CCL ranges absorbed two-thirds of it, but only by sliding a quarter down their curves.
The seller had better options
A limit order at the pool price would have filled as arbitrageurs moved FIN back up. A streaming swap on the base pool pays slip per sub-swap; 125,000 RUJI is about 10 % of the pool. The Liquidy router splits an order across FIN books and quotes before it executes.
Concentrated liquidity would have changed most
Range #66, which took half the sale, spans 0.01–15 USDC. The same capital concentrated around 0.12–0.22 quotes far more depth near the price and earns the same spread on a fraction of the price move.
The gap closed in about a minute
Two-thirds of the arbitrage profit went to whoever traded in the next block.
Method
Read-only queries against an archive of THORChain blocks, events and per-block state, and against a
THORNode at past heights. Pool price in USDC is the pool's RUNE balance ÷ RUJI balance × the RUNE
oracle price ÷ the USDC oracle price. FIN depth is the book as the contract's
book
query returns it: the first 100 levels, which reach about 10 % from the price on both sides.